Rideshare vs. Car Loan: Is Your Car Keeping You Broke?
Oct 18, 2026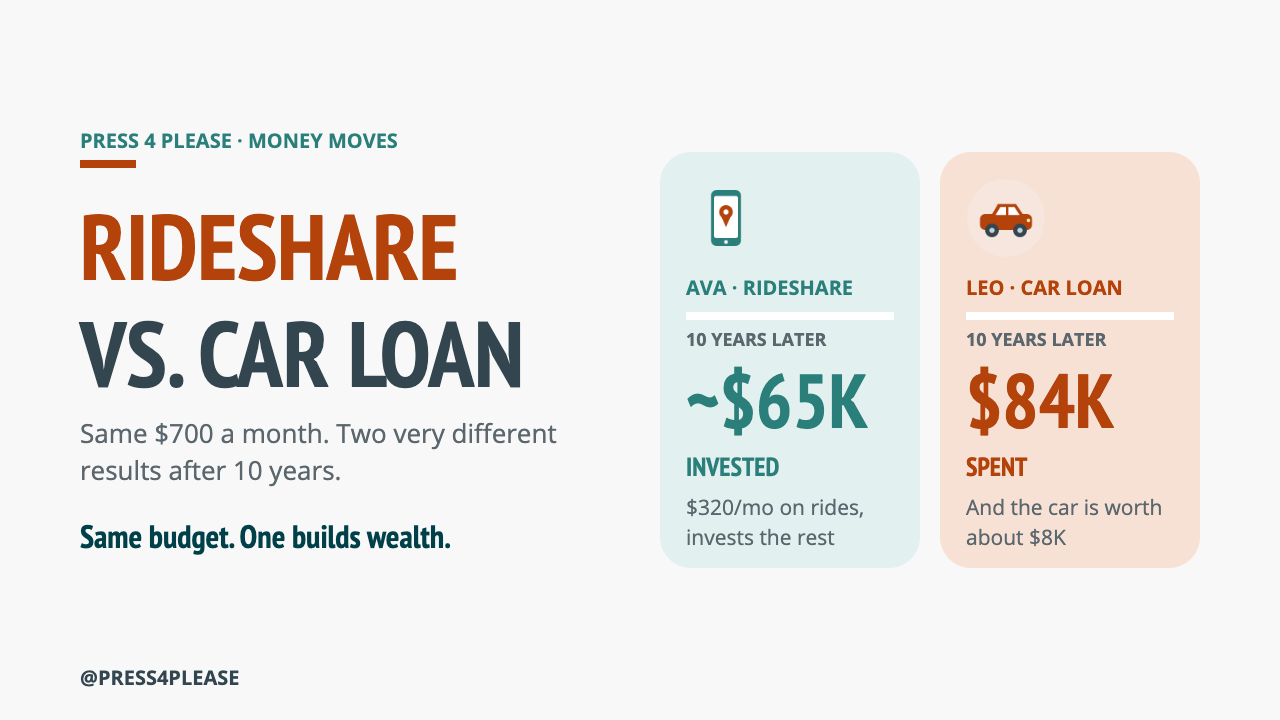
Most of us think about a car as a monthly payment. But the real question is bigger: what else could that money be doing?
Let's compare two people with the same $700 a month transportation budget and see where they land 10 years later.
Meet Ava: she skips the car payment
- Works remote most of the week
- Uses Uber or Lyft when she needs a ride, about $320 a month
- Invests the other $380 every month
Meet Leo: he drives everywhere
- Commutes downtown every day
- Financed a $35,000 car
- Pays about $700 a month for the loan, gas, insurance, upkeep and parking
10 years later
Ava has about $65,000 invested. She put in $45,600 ($380 a month for 120 months), and at 7% a year, roughly the stock market's long-run average after inflation, it grew to about $65,000.
Leo has spent $84,000 ($700 x 120 months), and the car is now worth about $8,000.
Same budget. One builds wealth. One loses value.
But a car isn't always the wrong choice
This isn't a "never buy a car" lesson. It depends on your life.
- Rideshare can win if you: work remote, live in a city with good options, or only drive a few times a week.
- A car can make sense if you: commute daily, have kids to drive, or live where rides are scarce or expensive.
Either way, the rule is the same: buy less car than you can afford, and invest the difference.
How to make the call
- Add up the full cost. Not just the payment: gas, insurance, parking, maintenance and registration.
- Compare it to how often you really drive. Check your last two months of trips.
- Pick the option that fits your life, not the one that looks good in the driveway.
- Invest whatever you save, every month. Automate it so it actually happens.
The takeaway
Your car costs more than the payment. Whatever you choose, make the money you don't spend on getting around go to work for you.
Want a simple place to start? Grab our free zero-based budget template, and follow @press4please for more simple money lessons.
Hypothetical example at a 7% annual return. Returns are not guaranteed, and real costs vary by city and vehicle. This article is for general information only and isn't financial advice.
Want a head start?
Grab the free zero-based budget spreadsheet: give every dollar a job before the month starts.